

By Jigsaw on Sep 22, 2026, 4:44:46 PM
For anyone hoping to buy their first home in Rugby, the latest property market figures make interesting reading.
Average house prices in the borough have fallen over the past year, including the average price paid specifically by first-time buyers. At the same time, private rents have continued to rise.
That does not automatically mean buying is now cheaper than renting, or that autumn 2026 is the right time for everyone to buy. Mortgage rates, deposits, income and personal circumstances all play an important part.
|
The key question |
What's happening to house prices in Rugby?
According to the latest Office for National Statistics figures, the average house price in Rugby was approximately £273,000 in July 2026.
That was 3.5% lower than in July 2025. By comparison, average house prices across the West Midlands increased by 1.5% over the same period.
Prices vary considerably according to property type. The latest Rugby averages were approximately:
|
Property type |
Average price |
|
Detached homes |
£447,000 |
|
Semi-detached homes |
£274,000 |
|
Terraced homes |
£215,000 |
|
Flats and maisonettes |
£126,000 |
These are average completed sale prices rather than asking prices, so individual properties can of course sell for considerably more or less. However, they provide a useful indication of what different budgets may currently be able to access in the Rugby market.
What are first-time buyers paying in Rugby?
The figures become particularly interesting when we look specifically at first-time buyers.
In July 2026, the average price paid by a first-time buyer in Rugby was approximately £230,000.
A year earlier, it was approximately £238,000. That represents an annual fall of around 3.3%.
For someone trying to get onto the property ladder, an £8,000 movement in the average purchase price can potentially affect both the size of the mortgage required and the deposit needed.
|
What might the deposit look like on £230,000? |
The mortgage options available at each deposit level will vary, and a larger deposit does not necessarily mean a particular mortgage will be suitable. Your income, credit commitments, employment situation and other circumstances will also affect what lenders may offer.
Meanwhile, rents in Rugby are still rising
While purchase prices have softened, the local rental market has been moving in the opposite direction.
The average private rent in Rugby reached approximately £1,049 per month in August 2026, according to the ONS.
That was up from £996 a month in August 2025, an increase of 5.4% in a year.
Average rents also vary significantly depending on the size of the home:
-
One bedroom - £755 per month
-
Two bedrooms - £933 per month
-
Three bedrooms - £1,123 per month
-
Four or more bedrooms - £1,656 per month
For someone currently renting and hoping to buy, rising rent can make saving for a deposit more difficult.
It is important, however, not to make a simple comparison between monthly rent and a mortgage repayment. Homeowners also need to consider insurance, maintenance, repairs and other costs associated with owning a property.
Does that make Rugby more affordable for first-time buyers?
Potentially - but the answer depends on what we mean by affordable.
Property prices are one part of the equation. The amount you can comfortably afford to spend on a home also depends on:
-
Your household income
-
Your available deposit
-
Existing loans and credit commitments
-
Childcare and other regular expenditure
-
The mortgage term
-
The interest rate available to you
-
The type and condition of the property
-
Other home-buying costs
Mortgage rates also remain an important factor in autumn 2026. Rightmove reported that the average two-year fixed mortgage rate had risen to around 5.29% in September, compared with 5.09% the previous month.
So while lower purchase prices may help some buyers, borrowing costs still need to be considered carefully.
|
A more useful question |
Could buyers have more negotiating room this autumn?
There are signs that buyers may currently have more choice than they have had in recent years.
Rightmove reported in September that the number of homes available for sale across Great Britain was at a 12-year high for the time of year.
At the same time, overall buyer enquiries were still 9% lower than a year earlier.
That does not mean every seller will accept a lower offer. The Rugby market contains many different neighbourhoods and property types, and desirable homes can still attract strong interest.
But a market with more properties competing for buyers can give purchasers more opportunity to compare homes carefully rather than feeling pressured into making an immediate decision.
There are also signs of the usual autumn increase in activity. Rightmove recorded a 5% increase in buyer demand during the first week of September compared with the end of August.
For buyers, that combination could mean more choice, but also increasing competition for the most attractive homes as autumn progresses.
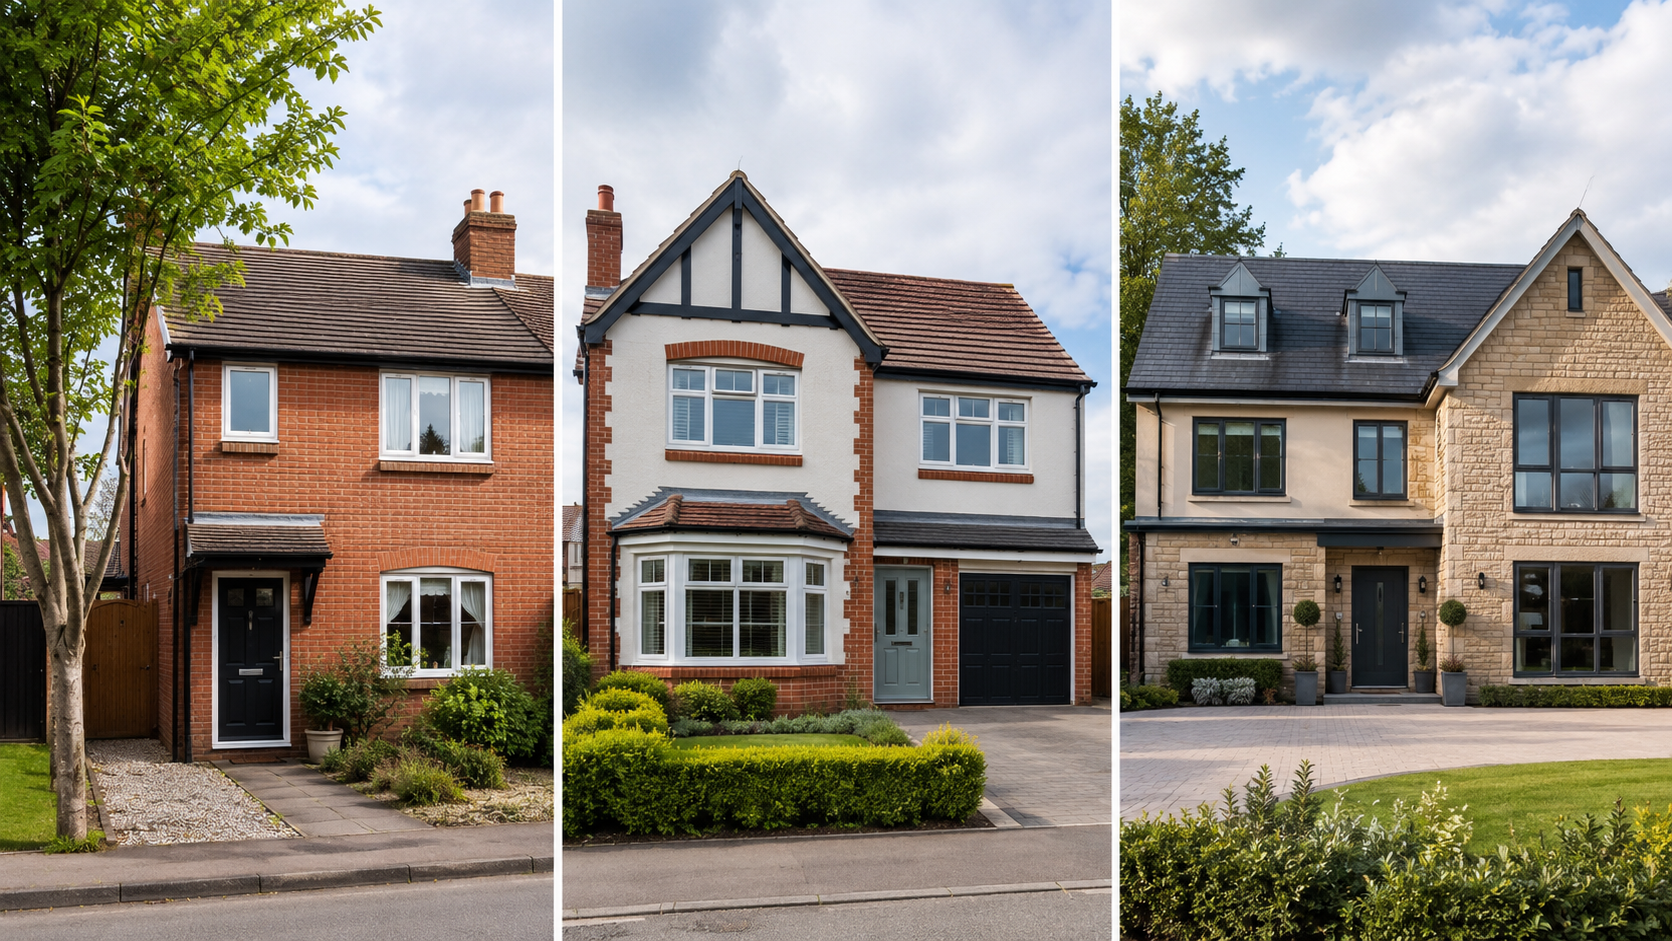
What could a first-time buyer budget buy in Rugby?
Recent average sale prices give us a useful guide.
Around £200,000
This sits below Rugby's overall first-time buyer average but around the level of the average terraced-property price.
Buyers at this budget may therefore be looking primarily at:
-
Terraced houses
-
Smaller homes
-
Apartments
-
Properties requiring some updating
-
Homes in lower-priced parts of the borough
Around £230,000
This is close to the current average price paid by a first-time buyer in Rugby. At this level, buyers may have a broader selection of terraced homes and potentially some smaller semi-detached properties depending on the location and condition.
Around £275,000
This is close to both Rugby's overall average house price and the current average price of a semi-detached property. A buyer with this level of budget could potentially have a much broader choice of family-sized homes, although availability and individual property prices will vary.
Rather than relying on an average figure, it can be useful to establish your realistic mortgage budget first and then see what that amount buys across different parts of Rugby.
Is Rugby good value compared with nearby areas?
One of Rugby's attractions is that it provides a broad mixture of property types while remaining well connected to Coventry, Warwickshire and further afield.
Within Rugby itself there are also very different markets.
Buyers might compare established areas such as Hillmorton and Bilton with newer developments around Cawston and Brownsover, or widen their search towards Dunchurch, Long Lawford and surrounding villages.
Someone who starts with a very specific location may discover that moving their search radius by only a few miles changes the amount of space available within their budget.
That is one reason it can be helpful to understand your borrowing position before becoming too focused on an individual property.
Should first-time buyers wait for prices or mortgage rates to fall further?
Trying to predict the perfect point at which to buy a home is extremely difficult.
House prices may rise or fall. Mortgage rates can change. Individual lenders may alter their affordability calculations or product ranges.
Meanwhile, your own circumstances may change too.
For most first-time buyers, the more useful questions are:
-
Can I comfortably afford the repayments?
-
Do I have enough deposit and money left for other buying costs?
-
Am I likely to stay in the property for a reasonable period?
-
Does the home meet my needs?
-
What mortgage options are actually available to me?
Those questions are far more important than trying to perfectly time the market.
How much could you borrow to buy in Rugby?
The average first-time buyer price of £230,000 does not mean that is automatically the right budget for you.
Some buyers may comfortably be able to spend more, while others may be better looking below that level.
Mortgage lenders assess affordability in different ways, and two people with the same salary and deposit can receive very different borrowing figures depending on their circumstances.
Before arranging viewings, it can therefore help to establish:
-
How much you may be able to borrow
-
What deposit you will need
-
What the monthly repayments could look like
-
What other buying costs you need to allow for
-
Which lenders are likely to suit your circumstances
An Agreement in Principle can also help you approach the property search with a clearer idea of your realistic budget.
Thinking of buying your first home in Rugby?
The current Rugby property market presents an interesting picture.
First-time buyer prices are lower than they were a year ago, while rents have continued to rise. Buyers also currently have a relatively large number of properties to choose from nationally, although mortgage affordability remains an important consideration.
Whether that creates an opportunity for you depends on your individual circumstances.
Jigsaw Independent Mortgage Specialists provides independent, whole-of-market mortgage advice to first-time buyers across Rugby, including Hillmorton, Bilton, Cawston, Brownsover, Dunchurch, Long Lawford and the surrounding area.
If you're thinking about buying your first home, speak to Jigsaw to understand how much you could borrow, what your monthly repayments could look like and which mortgage options may be available.
Mortgage advice in Rugby → www.jims.co.uk/mortgage-advice-rugby

What can £250,000, £350,000 or £500,000 buy across Coventry, Warwickshire and the West Midlands in 2026?
How To Get The Best Mortgage Rate As A First-Time Buyer
No Comments Yet
Let us know what you think